Strategies
World Quant

Strategies

Explore our diverse range of quantitative models designed for risk-adjusted returns in volatile market conditions.

PROPRIETARY ALPHA

Systematic Strategies for Sophisticated Markets

Leveraging advanced mathematics and high-performance computing to capture market inefficiencies in a Private 506(b) environment.

Statistical Arbitrage
ALGORITHMIC EXECUTION

Statistical Arbitrage

Mean Reversion & Pairs Trading

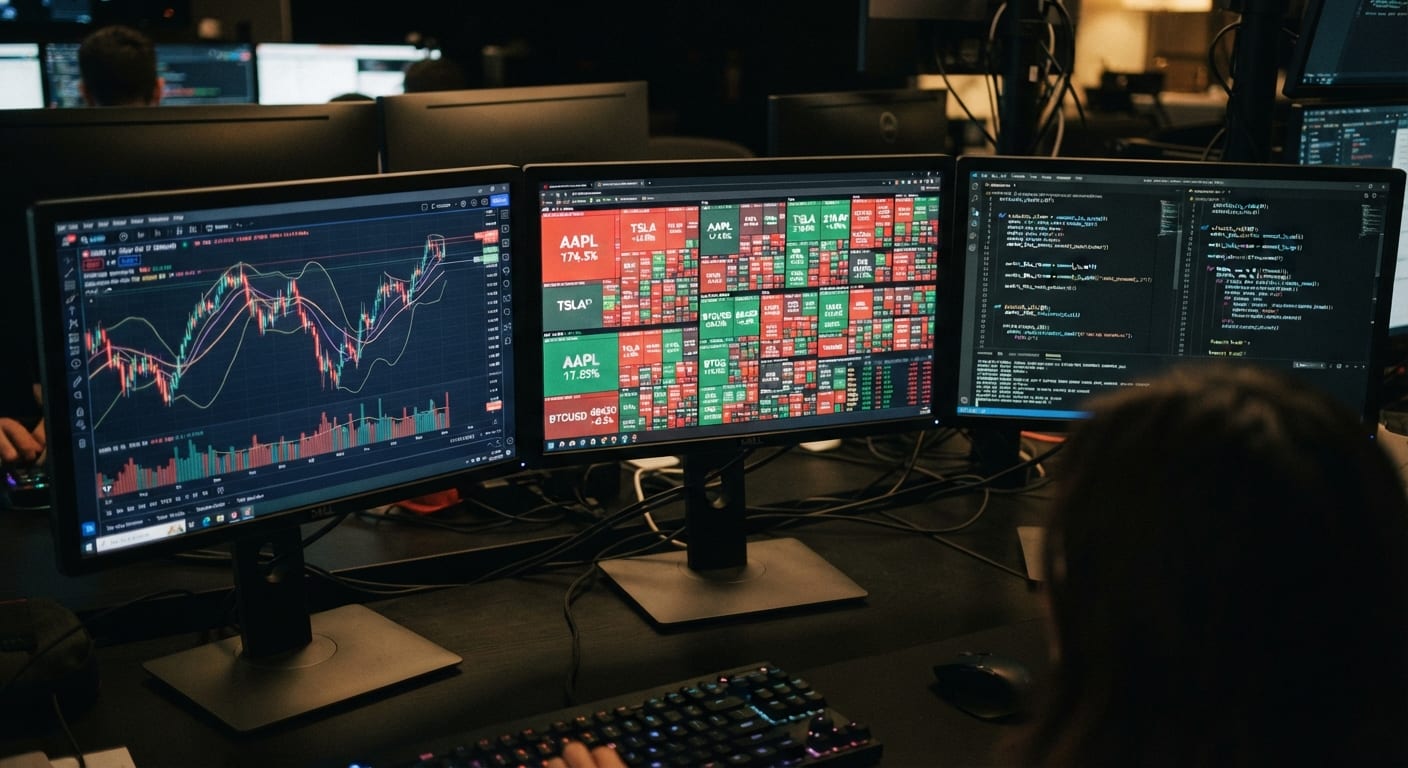
Our core strategy utilizes high-frequency data to identify short-term price dislocations across global equity and derivative markets. By applying rigorous mean-reversion models, we capture micro-inefficiencies while maintaining a market-neutral posture.
Predictive Analytics
ARTIFICIAL INTELLIGENCE

Predictive Analytics

Deep Learning & Pattern Recognition

We integrate deep learning models to process petabytes of alternative data, uncovering non-linear relationships that traditional models overlook. This allows us to forecast volatility shifts and directional momentum with high precision and automated risk management.

Quantitative Macro
GLOBAL MACRO

Quantitative Macro

Systematic Commodity & FX Positioning

Drawing on our Houston heritage, we specialize in commodity-linked quantitative models that capitalize on supply-chain shifts and geopolitical volatility. We combine fundamental economic theory with systematic execution to build resilient, diversified portfolios.